
 Last updated: August 2026
If you are researching the Utmost Spanish Collective Investment Bond, you are probably trying to answer three questions.
- How does it work?
- What are the tax advantages?
- Is it actually worth the cost?
This guide explains the structure, taxation, costs, flexibility and who it is genuinely suited to.
What Is a Spanish Investment Bond?
A Spanish investment bond is a tax-compliant life assurance wrapper designed to defer Spanish taxation. Rather than holding investments directly, the portfolio sits inside an insurance contract, allowing growth to roll up without annual taxation until withdrawals are made.
The Utmost Spanish Collective Investment Bond is one example of this structure and is designed specifically for residents of Spain.
What Is the Utmost Spanish Collective Investment Bond?
The Utmost Spanish Collective Investment Bond (SCIB) is a unit-linked, whole-of-life assurance policy issued by Utmost PanEurope in Ireland. It is structured to qualify for favourable treatment under Spanish income tax legislation.
Legally, the underlying assets are held by Utmost PanEurope while the investor remains the beneficial owner. This separation is what enables the tax deferral benefits.
The minimum investment is generally €100,000.
How the Tax Treatment Works
The key advantage is simple:
No withdrawals means no Spanish income tax.
Investment growth inside the bond rolls up without annual taxation. Tax is only triggered when money is withdrawn or the policy is surrendered, and only the gain element is taxable.
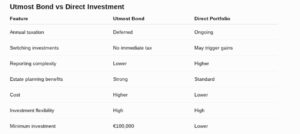
By contrast, direct investments are generally subject to taxation on dividends, interest and realised gains, and portfolio changes may trigger immediate tax liabilities.
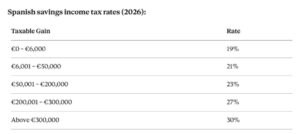
Each withdrawal is taxed proportionately. Part represents a return of capital, which is not taxed, and part represents investment gain, which is taxable.
Utmost currently deducts 19% withholding tax on gains when withdrawals or surrender occur.
Modelo 720 and Reporting Obligations
One of the practical advantages of the structure is simplified reporting.
Utmost reports policy values annually through Modelo 189. As a result, Spanish tax-compliant policies of this type generally do not require separate disclosure under Modelo 720.
For many expatriates, this can simplify annual tax reporting considerably.
Investment Flexibility
The bond operates on an open architecture basis and offers access to a broad range of Spanish-compliant UCITS funds.
Key features include:
- Fund switching without triggering immediate Spanish tax.
- Additional premiums from €20,000.
- Regular withdrawals.
- Discretionary manager appointments.
- Ongoing portfolio adjustments.
Utmost also provides access to its Wealth Interactive platform, allowing investors to:
- View valuations.
- Access transaction history.
- Download documents.
- Review fund factsheets.
Quarterly statements and annual tax certificates are provided.
Estate Planning Features
As the structure is a life assurance contract, it provides several planning benefits:
- Policies can be held jointly.
- The surviving owner can continue the policy after first death.
- Beneficiaries can be nominated.
- Death benefits are paid at 101% of surrender value.
These features can assist with succession planning, although the interaction with Spanish inheritance tax rules will depend on individual circumstances.
Security and Regulation
The Central Bank of Ireland regulates Utmost PanEurope.
Policyholder assets are legally segregated from company assets and receive priority in the event of insolvency.
There is no investor compensation scheme applicable to the structure and investments remain subject to market risk. Capital is not guaranteed and the value of investments can fall as well as rise.
Charges
The Utmost Spanish Bond is not a low-cost structure. Its value lies in tax efficiency and planning flexibility rather than headline charges.
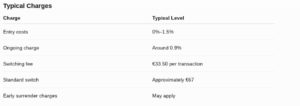
Underlying fund costs and adviser fees are additional.
Total costs will normally exceed 1% per annum and investors should request a full illustration before proceeding.
Advantages and Disadvantages
Advantages
✓ Tax deferral
✓ No immediate tax when switching funds
✓ Open architecture investment choice
✓ Simplified reporting
✓ Estate planning benefits
✓ Joint ownership available
✓ 101% death benefit
✓ Suitable for long-term planning
Disadvantages
✗ More expensive than direct investing
✗ Not ideal for smaller portfolios
✗ Investments remain exposed to market risk
✗ Early surrender charges may apply
✗ More complex than a standard brokerage account
Who Is It Suitable For?
Typically suitable for:
- Spanish residents with €100,000 or more to invest.
- Medium and long-term investors.
- Investors seeking tax-deferred growth.
- Those wanting portfolio flexibility without tax on fund switches.
- Individuals working with advisers or discretionary managers.
Who Is It Not Suitable For?
Generally unsuitable for:
- Short-term investors.
- Those seeking guaranteed returns.
- Investors requiring unrestricted access.
- Smaller portfolios where costs are disproportionate.
- Investors focused solely on minimising fees.
Three Things Worth Knowing Before Investing
Tax Deferral Is Not Tax Avoidance
The bond does not eliminate tax. It delays it.
The advantage is that investments compound before tax becomes payable.
Costs Are Layered
The headline charge is only part of the picture.
You should also consider:
- Adviser fees.
- Fund charges.
- Switching costs.
- Potential surrender charges.
Early Exit Can Be Expensive
Depending on the charging structure selected, surrender charges may apply.
Always understand the exit terms before proceeding.
Alternatives to the Utmost Spanish Bond
Depending on your circumstances, alternatives may include:
- Direct investment portfolios.
- Lombard International Spanish Bond.
- Prudential International Spanish Bond.
- Moventum platforms.
- Standard brokerage accounts.
- Spanish bank investment portfolios.
The best solution depends on portfolio size, tax residency, income requirements and estate planning objectives.
Our Verdict
The Utmost Spanish Collective Investment Bond is one of the strongest Spanish tax-compliant structures available for expatriates with six-figure portfolios.
Its value does not come from investment performance, which depends entirely on the underlying assets. Rather, its value comes from tax deferral, flexibility and administrative simplicity.
For long-term investors with €100,000 or more, these advantages can outweigh the additional costs.
For smaller portfolios or shorter investment horizons, simpler and lower-cost solutions may be more appropriate.
Used appropriately, it is an excellent structure.
Used unnecessarily, it can add complexity and cost without delivering sufficient benefit.
Useful Links
The Wealth Genesis | Spanish Bond
The Wealth Genesis | Can Your UK Adviser Still Advise You if You Live in Europe?
Utmost | Europe Expatriate Solutions